


 Locations



Allied Properties (AP-UN-T) has begun the hunt for a new CEO and announced major board changes as the debt-burdened office REIT continues its push to strengthen its balance sheet.
Cecilia Williams, who has held the role of CEO and president since 2023, will continue in place as the leadership search is undertaken, Allied said.
“Leading Allied is a privilege, and I value the dedication and resilience of our team through a period of significant change,” Williams said in a media announcement. “Throughout this transition, I remain focused on supporting our people and progressing our business priorities.”
In thanking Williams, board chair Jennifer Tory acknowledged her leadership during a "challenging time" for Allied. Last month, the REIT abruptly slashed its distributions by 90 per cent and announced an aggressive $750 million to $1.5 billion disposition program to sell off assets and reduce its debt.
Allied ended Q3 with net debt at 12.5 times annualized EBITDA, a level CFO Craig MacPherson called "far too high," in its quarterly conference call.
“Collectively, we have been taking steps to resolve significant issues and to strengthen the foundation of the company for this next phase, and we appreciate her continuing to lead the business while we select a successor," Tory said in the announcement.
Board changes
Allied also announced that board members Hazel Claxton and Kay Brekken have stepped down, and Leonard M. Abramsky and Dayna Gibbs have been appointed to its board of trustees.
The REIT said Claxton and Brekken are leaving to focus on other commitments.
New board member Abramsky is a former managing partner at Brookfield Financial/Brookfield Real Estate Financial Advisor. He has over 40 years of experience in investment banking and commercial real estate, Allied noted in the announcement.
He most recently served as a trustee of a number of TSX-listed REITs.
Joining him on the board, Gibbs is the former COO of Summit Industrial Income REIT, which went private in 2023. Gibbs has served on the boards of numerous public, private and not-for-profit organizations, Allied said.
The board changes follow the notable appointment of former Crombie REIT CEO and president Donald Clow to the board of trustees last month.
On Oct. 19, Allied announced Clow would join the board as the chair of the governance, compensation and nomination committee, effective Jan. 1, 2027.
Allied also appointed Mario Barrafato as chair of the audit committee.
Clow expected to take on board chair role
Yesterday, the REIT announced Clow has been appointed board vice-chair and is expected to succeed Tory in the chair role following the company's AGM in May 2027.
"As part of the Strategic Plan and leadership renewal process, two new trustees were named over the past few months, and a new CFO was hired," Allied said.
"The company also expects a majority of Board seats to be held by new trustees following the company’s annual general meeting in May 2027 and has appointed Donald Clow as Vice-Chair.
"In this role, Mr. Clow and the Chair will work closely to provide leadership and support to management and trustees in executing the Strategic Plan and selecting a new CEO."
'Difficult decisions' in the future
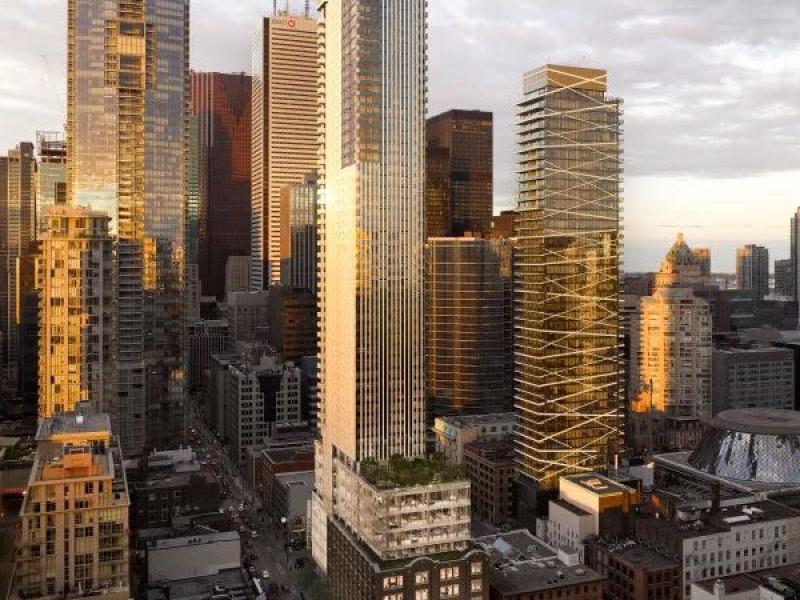
In its Q3 financial report, Allied announced it was selling off its Toronto House/19 Duncan property in a $325-million deal expected to close in Q4. Green Street later revealed Groupe Mach as the buyer of the 58-storey mixed-use asset.
When asked about strategies under consideration as the REIT continues attempts to strengthen its balance sheet during Allied's Q3 conference call, the outgoing CEO ruled out the possibility of a sale of the REIT.
"At this point, we're always assessing all of the strategic alternatives available to us," Williams said. "If you mean specifically a sale of the company, now is not the time to pursue that. We would not achieve value for our unitholders."
In yesterday's announcement, Clow said "difficult decisions" lay ahead.
“The Board continues to help management work through some very challenging business situations and make some very difficult decisions, laying the groundwork for rebuilding value for unitholders over time,” Clow said. “Together, with my fellow trustees and management, we will continue this progress towards an improved financial performance.”



 Industry Events
 Locations

